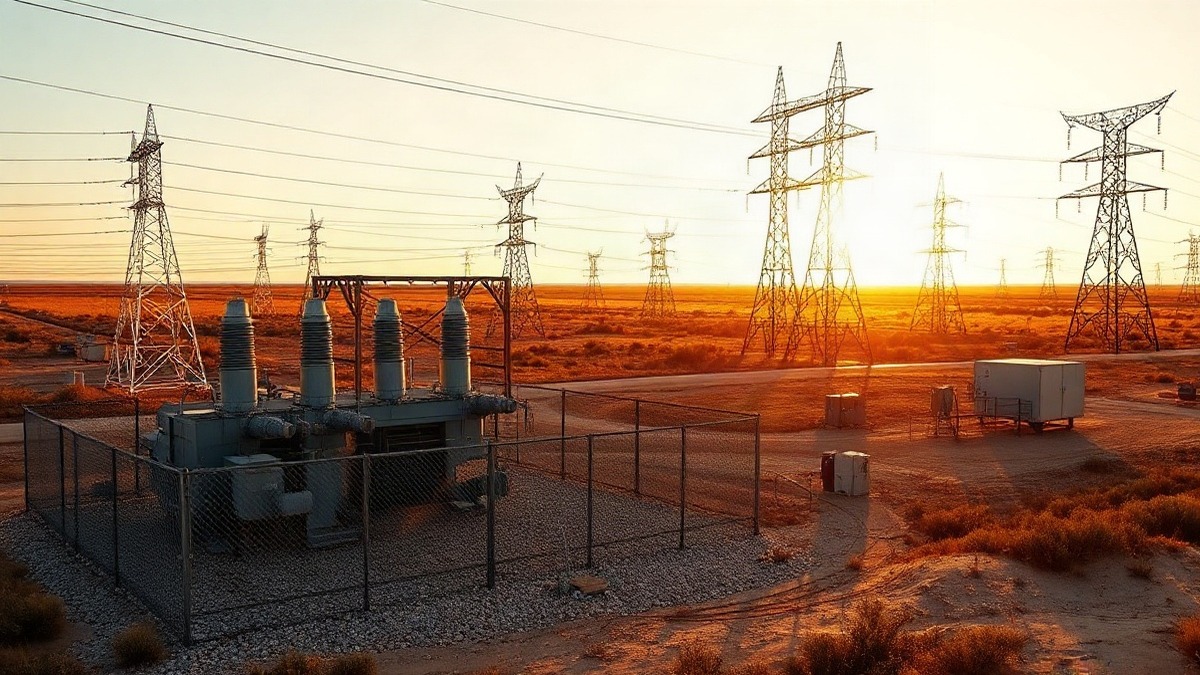
Think of IREN as the landlord who secured the heavy industrial power lines before everyone else decided to build a data center. Originally formed as a Bitcoin miner, the business rebuilt itself to rent high-performance computing to artificial intelligence developers. The model is simple: IREN buys land where electricity is cheap, builds dedicated high-voltage substations that hook directly into the regional power grid, and fills the floor with liquid-cooled Nvidia systems. It sells raw compute capacity by the hour to customers like Microsoft and Cohere. While Bitcoin mining still accounts for the majority of current receipts, the power infrastructure beneath those racks is what equity investors are pricing.
On Oct. 11, The Information reported that Anthropic signed a multi-year cloud contract with IREN. The report cited unnamed sources and omitted every structural detail: no dollar value, no term length, no site location, and no megawatt total. The stock, which had dropped nearly 15% across the 3 previous sessions, climbed roughly 4% intraday when the report circulated before giving up most of the advance to sit up roughly 1%. The pop faded quickly, but IREN was the lone gainer among peers; competitors like Nebius, CoreWeave, and Cipher Mining all traded down, while TeraWulf, which already holds a confirmed Anthropic lease, stayed flat.
The muted reaction reflects an unresolved question at the center of the story. Back on Aug. 27, IREN told investors it had signed a multi-year deal with an unnamed leading frontier AI lab. If Anthropic is simply the tenant behind that August disclosure, the headline represents a relabelling of existing backlog rather than an influx of fresh revenue. A name change on a ledger does not accelerate cash flow.
| Price LIVE | $35.19 |
| Market Cap | $14.1B |
| Forward P/E | N/A |
| Total Revenue (TTM) | $707.0M |
| 52-Week Low | $28.93 |
| 52-Week High | $76.87 |
| Analyst Consensus | Buy (18 analysts) |
| Analyst Target Mean | $78.14 |
Yet the broader appetite from labs explains why these rumors carry weight. Frontier model builders are locked in a race where speed to an energized substation matters far more than saving a few pennies per chip. Every month an algorithm sits waiting for utility approval is a month of lost inference revenue. Anthropic alone has mapped out roughly $518 billion in planned infrastructure spending across 6 partners, with roughly 80% locked into non-cancelable commitments. Its footprint scales from 1.4 GW last year toward more than 15 GW by 2028.
That urgency previously drove IREN's anchor transaction: a roughly $9.7 billion, 5-year deal with Microsoft for 200 MW of IT capacity at Childress, Texas. That contract included a 20% customer prepayment and is designed to yield about $1.94 billion in annual recurring revenue once fully commissioned, having delivered its initial 50 MW phase in August. On recent 3-year deals, IREN generates more than $20 million of revenue per megawatt, achieving roughly a 2-year payback while upfront prepayments cover 45% to 55% of GPU capital spending.
Still, the machinery requires massive external capital, and lenders look at the tenant rather than the silicon. When financing identical hardware, the interest rate is dictated by who signed the lease. IREN raised $3.6 billion of investment-grade GPU debt at 6.0% backed by its Microsoft contract. For its Mackenzie campus in British Columbia, a $2.4 billion facility backed by Blue Owl and PIMCO carried a 9.0% fixed rate. That 3 percentage point spread is the tax paid for unrated counterparty risk.
To force a genuine re-rating, IREN has to turn paper promises into billed receipts. The company reports contracted annual recurring revenue of about $4 billion against an operating run-rate of roughly $1 billion. For FY26, AI cloud revenue reached $128.8 million out of $707 million in total revenue, meaning legacy crypto mining continues to fund the transformation. The stock will not climb to higher valuation multiples simply because another prominent logo is whispered in the press; operating ARR must actively converge with contracted totals.
A dedicated short seller would point out that IREN is funding an infrastructure marathon with expensive paper while generating steep losses. The business recorded a net loss of $702.6 million last year, weighed down by $638.8 million in impairments on retired mining equipment, and posted negative $4.2 billion in trailing free cash flow. Management leaned on capital markets heavily in 1 quarter alone, issuing $2.1 billion in equity and $3.0 billion in convertible notes against a debt load of $7.8 billion. If contracted ARR does not step up when IREN next reports, the bears get their proof. And if the Anthropic headline turns out to be the August contract under a different name, equity holders absorb another round of dilution long before the 2 GW Sweetwater Hub delivers power.
The immediate test is whether contracted annual recurring revenue steps up when the company next reports. Without hard numbers on the tape, a headline is just an expensive rumor.
Disclosure: The Signal holds no position in IREN. Positions may change. This is not financial advice.